






Grudging UBS support for capital compromise before vote

The top leaders of UBS bank indicated at least some backing for a recent proposal from Swiss lawmakers to soften planned new capital requirements, just days before a crucial political vote on the matter.
Select your language
Generated with artificial intelligence.
Listening:
Grudging UBS support for capital compromise before vote
Chief Executive Officer Sergio Ermotti said the idea to let UBS use a form of debt known as AT1 bonds to meet some of the new requirements would be “bearable” for the lender, according to an interview in Neue Zürcher Zeitung published Sunday. The remarks came shortly after chair Colm Kelleher used similar wording.
Both Ermotti and Kelleher said they still wouldn’t be happy to see the plan get turned into law.
The grudging support is the clearest indication yet that UBS would temper its vocal opposition to Switzerland’s planned banking overhaul if the country were to adopt the AT1 plan. The parliament’s upper house is set to vote on the matter on September 23.
More
Why a monster UBS bank scares Switzerland
Adoption of the AT1 proposal would boost the likelihood that the ultimate capital requirements on UBS will be less hefty than what the government is seeking to impose. That initiative would supplant a draft bill submitted by the government, which the lender has repeatedly rejected as too burdensome.
Lawmakers face choice
It’s unclear which proposal will ultimately prevail as the vote this week will only be the next step in a long and complex legislative process. The government has previously rejected the AT1 solution.
The lawmakers will choose between the government plan, another option that would increase capital requirements slightly less, and the AT1 compromise.
The Swiss government wants to pass a law that would require UBS to back 100% of the value of its foreign subsidiaries with equity capital known as CET1 at its domestic unit. That would be a big increase from the current rule that only prescribes backing of 60%, parts of which can be met with AT1 bonds.
More
How to tame UBS without making the bank toothless
By contrast, the counterproposal put forward by the Economic Affairs and Taxation Committee of the Senate would allow the bank to use AT1 bonds to meet as much as half of the 100% capital backing for foreign units.
Third option
The Senate will also debate a third plan, which would raise the requirement to 90%.
Ermotti said in the NZZ interview that the worst-case scenario for UBS would be adoption of the government proposal, and he also said he’s opposed to the 90% plan.
He declined to say which capital rules he would see as an ideal outcome for UBS.
“If I did so and the political solution ended up matching that figure, it would be said that the political establishment had caved in and done exactly what UBS dictated,” Ermotti said. “The current situation is essentially: UBS against the rest. In such a scenario, it is extremely difficult to keep a cool head.”
In any case, the stakes are high for UBS and its investors.
Analysts at RBC calculated a 10% hit to the bank’s earnings per share if the plan for a full capital backing of the foreign units was implemented.
Not fully happy
“Are we happy about it? No, we are not,” Ermotti said in the interview, referring to the AT1 proposal. “It’s still a blow but one that is bearable,” he said.
“We helped save Switzerland from a reputation-damaging debacle during the Credit Suisse rescue,” Ermotti also said. UBS agreed to buy the rival in early 2023 through an emergency deal engineered by the Swiss government, which was concerned that the large bank’s troubles could spiral into a full-blown financial crisis.
The Credit Suisse takeover has made UBS an even bigger bank and the government argues it should hold more capital to ensure any potential future crisis doesn’t turn it into a threat for Switzerland.
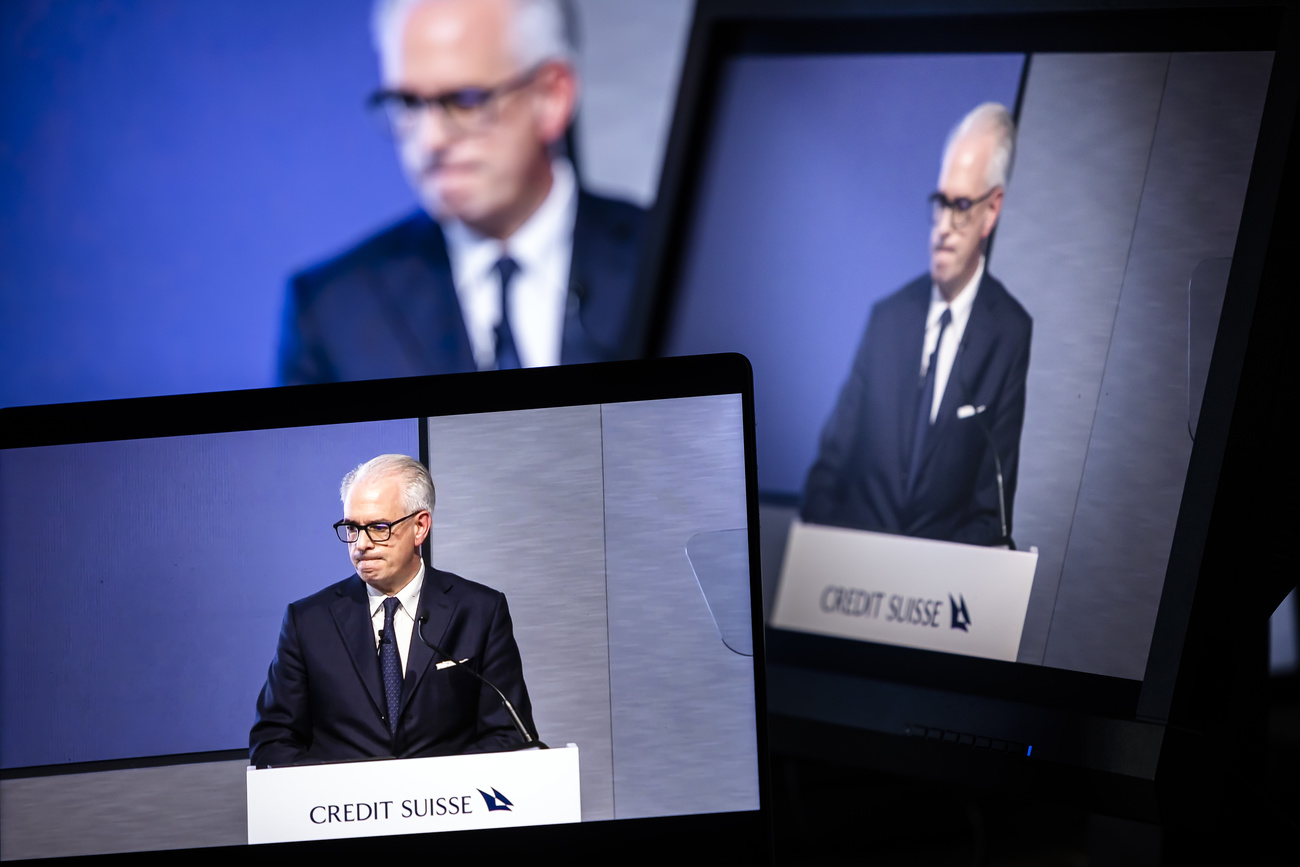
More
Where did it all go wrong for Credit Suisse?
UBS has been seeking to convince the Swiss government and the country’s regulators that the planned overhaul goes too far and would damage not only UBS but also the national economy.
Holding more capital for its foreign units would make growth more costly for UBS and lower its return on equity.
Since the financial crisis almost two decades ago, UBS has been downsizing its investment bank and has focused even more on wealth management and asset management.
UBS’s investment banking operations — which include equities trading, foreign exchange and advisory — are much smaller compared to Credit Suisse in comparison to the overall group.
Competitive disadvantage
Still, a 100% capital backing of the US business would post a disadvantage in the country with the world’s deepest capital markets for UBS.
Ermotti said the AT1 compromise would still be a problem as UBS would have to amass another $13 billion in additional Tier 1 capital, or $2 billion per year considering a phase-in period.
Ermotti reiterated that the Swiss National Bank and Switzerland’s financial regulator FINMA deserve part of the blame for the demise of Credit Suisse.
The CEO said in the interview that UBS investors have had to pay some $15 billion for Credit Suisse’s recapitalization and restructuring. UBS will only reach the same return on equity it had prior to the Credit Suisse takeover at the end of this year, he said, rebuffing the notion that UBS bought Credit Suisse on the cheap.
Asked about his future at UBS, Ermotti said that ending his tenure as CEO is “not a topic.”
Ermotti initially led UBS from 2011 to 2020. The Swiss executive took the helm a few years after the bank was rescued by the Swiss government during the financial crisis. Ermotti returned as CEO after UBS took over Credit Suisse.

More
Swiss parliament vote on UBS capital rules postponed
–With assistance from Sam Nagarajan.
(Updates with context starting in third paragraph.)
©2026 Bloomberg L.P.
In compliance with the JTI standards
More: SWI swissinfo.ch certified by the Journalism Trust Initiative

You can find an overview of ongoing debates with our journalists here . Please join us!
If you want to start a conversation about a topic raised in this article or want to report factual errors, email us at english@swissinfo.ch.